
BIX ARTICLE
Malaysia’s bonds brace for bumpy ride
Sep 14, 2026
|
7 min read
Featured Posts
Social Bonds Illustrative Use-Of-Proceeds Case Studies Coronavirus
Jul 06, 2020
|
2 min read
Sustainable Banking Network (SBN) Creating Green Bond Markets
Jul 06, 2020
|
2 min read
Why is Inflation Making a Big Comeback After Being Absent for Decades in the U.S.?
Mar 24, 2022
|
7 min read
SC issues Corporate Governance Strategic Priorities 2021-2023
Mar 29, 2022
|
3 min read
THE Malaysian bond market is likely to remain selective through year-end as global yields, heavier domestic duration supply and shifting expectations for interest rates keep investors cautious.
Longer-dated bonds face the greatest pressure, although Malaysia’s solid fundamentals and attractive relative value should continue to support demand into 2027.
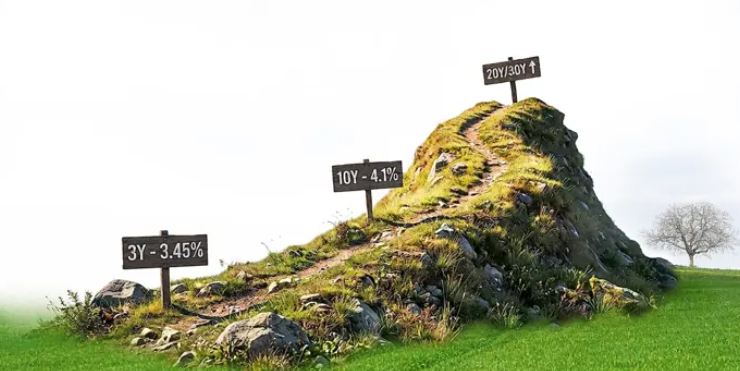
CIMB Research expects a bear steepening in Malaysian Government Securities (MGS) to have further room to run, with heavier duration supply, potentially wider pre-auction concessions and higher global yields reinforcing upward pressure on the long end.
It raises its end-2026 MGS yield forecasts to 3.45% for three-year paper and 4.1% for 10-year bonds, while expecting the overnight policy rate (OPR) to remain at 2.75% at November’s Monetary Policy Committee meeting.
The repricing is already well under way. MGS yields have climbed sharply since mid-July, with selling pressure intensifying in August at the long end.
Yields on 20-year, 30-year and 10-year MGS rose 21 basis points (bps), 15 bps and 16 bps, respectively, during the month, marking their sharpest monthly increases since September 2022, September 2023 and October 2024.
The pressure has carried into September, pushing the 10-year MGS yield to 3.94%.
CIMB Research says domestic duration supply, corporate issuance and higher global yields are combining to keep the market under pressure.
“A duration-heavy supply calendar keeps the long end under pressure,” it says.
The research house points out that 11 of 12 long-dated MGS/Government Investment Issues (GII) auctions involving 10-year paper and beyond, excluding new issues, have seen yields rise ahead of the auction.
The average concession has widened to 5.2 bps, compared with 4.5 bps in 2025 and 3.3 bps in 2024, and is materially higher than the 2.9 bps average recorded for bonds below 10 years.
With eight of the remaining 11 MGS/GII auctions concentrated in the 10- to 30-year segment, CIMB Research expects supply-driven pressure to remain most pronounced at the long end through year-end.
There is also room for further adjustment. The 10-year-to-30-year spread stands at 37 bps, below its three-year average of 43 bps, suggesting that ultra-long-duration bonds could continue to cheapen.
Corporate issuance adds another layer of competition for duration.
Around half of year-to-date corporate bond supply is in longer tenors, directly competing with MGS and GII for investor demand. That competition could become more intense in the final quarter, when corporate issuance typically accelerates.
“Corporate supply adds competition for duration,” CIMB Research says.
Short is compelling
For investors looking for alternatives to sovereign duration, shorter-dated high-quality corporate bonds are becoming more compelling.
CIMB Research notes that these securities offer a 15 bps to 35 bps pick-up over sovereigns in the five-year-and-below segment.
For example, a five-year AA3 corporate bond yields 3.96%, compared with 3.94% for 10-year MGS.
That makes shorter corporate paper increasingly attractive as investors seek to reduce duration risk amid the broader repricing in global term premia.
External factors are, meanwhile, making the environment more challenging.
While the correlation between MGS and United States Treasuries (USTs) has weakened over the past two months, CIMB Research says global monetary policy is still exerting pressure on Malaysian bonds.
Oil-driven inflation concerns have pushed global monetary policy in a more hawkish direction, with the global gross domestic product-weighted policy rate rising 61 bps year to date.
Expectations for US Federal Reserve (Fed) and Bank of Japan policy, together with lingering fiscal concerns, have lifted both UST and Japanese Government Bond (JGB) yields.
“MGS therefore faces compounding external pressure: elevated UST yields sustain term-premium pressure, while higher JGB yields raise the opportunity cost of overseas duration, increasing the risk of yen carry-trade unwinds and Japanese repatriation flows,” CIMB Research says.
This matters for Malaysia, given the sizeable presence of Japanese investors. They held US$7bil of Malaysian debt securities in 2025, equivalent to nearly 9% of total foreign holdings.
On the domestic front, CIMB Research says Malaysia remains something of an exception in monetary policy, although the tone is becoming less accommodative.
Bank Negara Malaysia kept the OPR at 2.75% on Sept 3 but signalled a hawkish tilt, with greater confidence in economic growth shifting attention towards inflation.
That raises the possibility of a 25 bps reversal of the July 2025 insurance cut in the first half of 2027 should inflation become broad-based.
Interest rate swaps (IRS) have already partially priced in the risk, with the one-year IRS at 3.64%, above its 2025 high.
Swing factor
Kenanga Research sees global rates as the key near-term swing factor for Malaysian bonds.
US fiscal concerns and higher term premia are likely to keep investors selective towards duration, while geopolitical tensions could add further volatility.
It expects the Fed to hold rates through the rest of 2026, with the first cut only coming in the second quarter of financial year 2027, later than current market pricing suggests.
Until that easing cycle comes into view, demand for local bonds is likely to remain uneven, with global duration repricing exerting a greater influence on capital flows than improving liquidity conditions.
Still, Malaysia has some strong cards to play.
Resilient economic growth, moderating inflation, stable sovereign ratings, a well-anchored monetary policy framework, healthy external balances, attractive real yields and ample domestic liquidity leave the country well positioned against regional peers on relative value.
“Malaysia’s fundamentals argue for patience rather than an imminent inflow wave,” Kenanga Research says.
That patience is particularly relevant after a dramatic turnaround in foreign flows.
Foreign investors become net buyers of Malaysian bonds in August, bringing in RM15.9bil after net outflows of RM5.6bil in July. The inflow is the third-largest monthly inflow on record and the biggest since September 2013.
Total foreign holdings rise to RM320.1bil from RM304.2bil, lifting foreign ownership of outstanding debt to 13.5% from 12.9%.
However, the recovery in MGS holdings remains incomplete, with holdings at RM235.2bil, still below June’s RM237.6bil.
The August inflows are broad-based, spanning MGS, GII and corporate bonds and sukuk (CBS). MGS sees RM5bil of inflows after July’s RM7.4bil outflow, while GII records RM5.6bil of inflows and CBS attracts RM4.8bil.
Kenanga Research says the rebound reflects renewed demand for duration as concerns over US fiscal sustainability push long-end UST yields and term premia higher, while a stronger ringgit and Malaysia’s improving external position add to the appeal of local-currency debt.
But the research house cautions against treating August’s surge as the beginning of a sustained foreign buying cycle.
“The near-term risk is that August’s inflow proves a one-off duration trade rather than the start of a sustained trend.”
Foreign participation is therefore expected to build only gradually into 2027, leaving investors to navigate a bond market where shorter corporate duration looks increasingly defensive, while the long end remains vulnerable to supply and global yield pressures.
Disclaimer
YOU MAY ALSO LIKE
ARTICLE
Sep 14, 2026
|
7 min read
ARTICLE
Sep 09, 2026
|
2 min read
ARTICLE
Sep 07, 2026
|
9 min read
ARTICLE
Sep 07, 2026
|
4 min read