
BIX ARTICLE
All eyes on Warsh
Sep 14, 2026
|
7 min read
Featured Posts
Social Bonds Illustrative Use-Of-Proceeds Case Studies Coronavirus
Jul 06, 2020
|
2 min read
Sustainable Banking Network (SBN) Creating Green Bond Markets
Jul 06, 2020
|
2 min read
Why is Inflation Making a Big Comeback After Being Absent for Decades in the U.S.?
Mar 24, 2022
|
7 min read
SC issues Corporate Governance Strategic Priorities 2021-2023
Mar 29, 2022
|
3 min read
WASHINGTON: Central banks from much of the Group of Seven (G7) face a pivotal week as mounting inflation risks heap pressure on them to raise interest rates.
Three decisions, starting with the Federal Reserve (Fed) on Wednesday and followed on successive days by peers in the United Kingdom and Japan, may recast the global monetary policy landscape for the rest of 2026 and beyond.
The United States will be most closely watched in the wake of a higher-than-expected core inflation reading last Friday.
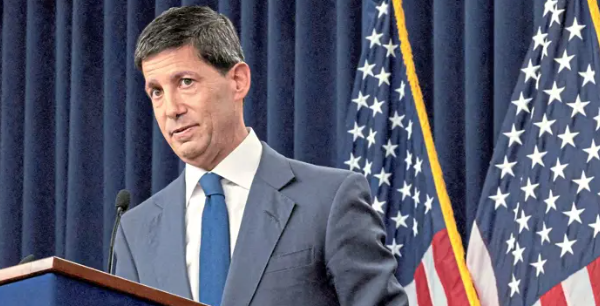
That stoked investor bets that Fed chairman Kevin Warsh (pic) and his colleagues will raise their benchmark rate, probably in defiance of President Donald Trump’s wishes.
A Bank of England (BoE) rate increase this Thursday isn’t anticipated, but with three officials having favoured such a move at the late-July meeting, and with price risks simmering, the prospect of shifting toward a hike as soon as November can’t be excluded.
The Bank of Japan (BoJ), meanwhile, is widely predicted to raise its key rate at the end of the week after a raft of supportive data, including the nation’s biggest jump in wages in nearly three decades.
With oil emphatically above US$100 a barrel again and the Middle East war apparently reigniting, any hope among policymakers for a respite in global price pressures seems faint for now.
After European Central Bank (ECB) officials tightened last Thursday, the second such move since the outbreak of the Iran conflict, investors may well end the week with the picture of an increasingly synchronised hawkish policy stance across the G7 coming into clearer focus.
The club’s other institution, the Bank of Canada, is moving that way too.
Minutes of its decision earlier this month, when officials kept rates steady but emphasised inflation concerns, will be published on Wednesday.
“The unfiltered market signal is clear: investors want and expect the FOMC to hike.
“If it doesn’t, Warsh will lose credibility in the eyes of market participants,” said Bloomberg Economics analysts Anna Wong, Andrew Sacher and Eliza Winger.
Elsewhere, Chinese industrial data, inflation numbers from the United Kingdom and Canada to India and Japan, and a probable rate cut in Brazil will be among the highlights.
Warsh said last month that the Fed would “have work to do” if it couldn’t “be confident that underlying inflation is moving to our objective, clearly and at sufficient speed”.
Last Friday’s inflation data offered no such comfort.
Investors and economists now see it as a near certainty the US central bank will raise interest rates for the first time in three years.
Support for such a move had been building at the Fed, even before the latest figures.
In July, three officials dissented against the decision to hold rates steady and instead would have preferred to hike.
Policymakers on Wednesday will also release updated projections for economic growth, inflation and the outlook for rates.
The week’s US data docket includes retail sales, which are expected to rebound in August, as well as fresh figures on housing starts and industrial production.
In Canada, August inflation data today will give more evidence on the state of the economy entering a jittery third quarter, dominated by the escalating tariff war with the United States.
China’s data dump
The main focus of the week will be China’s August data dump tomorrow, set to provide the most comprehensive official look at what happened in the economy there last month.
Forecasts show that economists don’t expect much of a pickup from July, when the economy slowed almost across the board.
As has been the case all year, Chinese production and exports of artificial intelligence (AI)-related tech products have expanded rapidly, but the rest of the economy is in a funk.
India’s August inflation data, due today, will be watched to gauge if price pressures are broadening, which could offer clues on how soon the Royal Bank of India may raise rates.
On the same day, the Pakistan central bank will announce its rate decision, with economists expecting a hold.
The BoJ’s probable hike on Friday would be its second of the year.
That would take the policy rate to 1.25%, the highest level since 1995, and maybe provide more support to the yen, which has risen in recent weeks.
The same morning, the government will report national consumer price data for August, with inflation forecast to have risen 2% from a year earlier.
India, Japan and New Zealand will all report August trade data in the coming week, with Japan’s imports and exports expected to have continued the rapid growth they’ve shown all year when the data is released on Wednesday.
New Zealand on Thursday reports second-quarter gross domestic product growth, with the economy forecast to have expanded more slowly than in the first quarter.
That will be the last gross domestic product (GDP) release before the national election in November, and may be a factor for voters as they decide whether to re-elect Prime Minister Christopher Luxon.
Sri Lanka will also report GDP on tomorrow.
Europe, Middle East, Africa
UK releases will offer policymakers clues on the strength of price pressures before their rate decision later in the week.
Jobs numbers tomorrow are predicted to show roughly stable wage increases, while the following day, headline inflation is predicted to have quickened in August to 3.1%, a five-month high.
Beyond the outcome for rates, the BoE meeting will be watched for an annual announcement on how fast it plans to unwind bond holdings.
In the eurozone, meanwhile, in the wake of last Thursday’s rate hike, key numbers include industrial production and the ECB’s wage tracker, both due Wednesday.
Its measure of consumer-price expectations comes out this Friday.
ECB chief economist Philip Lane will address a two-day research conference that starts on Wednesday, while President Christine Lagarde and colleagues gather in Dublin for informal meetings with European Union finance ministers at the end of the week.
Swedish unemployment measures are scheduled for Wednesday and Thursday.
On the latter day, the Swiss government’s latest economic forecast comes out too.
Recent data there showed a noticeable pickup in inflation.
Further afield, Israel will release inflation figures tomorrow, with a small acceleration to 1.6% expected from 1.55%.
Since that’s still within the central bank’s range it may strengthen the case for renewed rate cuts, though price growth is expected to quicken toward year-end.
Finally, a couple of other monetary decisions are scheduled: In Peru, the first look at third-quarter economic activity tomorrow may see July GDP-proxy figures in line with June’s as the El Nino weather phenomenon continues to kick up supply disruptions.
Peru’s economy posted slightly better than expected second-quarter growth despite sluggish readings in June.
Along with the monthly economic activity indicator, the August jobs report for the capital city is also due.
The unemployment rate in Lima hit a record-low 4.7% in July.
Brazilian retail sales figures and July economic activity data set the table for the central bank’s rate decision on Wednesday.
Analysts and traders expect policymakers, led by governor Gabriel Galipolo, to deliver a fifth straight quarter-point rate cut, taking the Selic to 13.75%.
Tight monetary policy coupled with tapped-out households has LatAm’s No. 1 economy on course for a third year of slowing growth, although above-target inflation and sticky expectations will likely keep policymakers boxed in.
In Chile, minutes of the central bank’s September meeting, which saw a sixth straight hold at 4.5%, aren’t likely to depart from the cautious and contingent view communicated in the post-decision statement.
The institution has cut its 2026 GDP estimate to between 0.25% and 0.75% from the prior forecast of 1% to 1.75%. — Bloomberg
Disclaimer
YOU MAY ALSO LIKE
ARTICLE
Sep 14, 2026
|
7 min read
ARTICLE
Sep 14, 2026
|
7 min read
ARTICLE
Sep 09, 2026
|
2 min read
ARTICLE
Sep 07, 2026
|
9 min read