
BIX ARTICLE
Monthly Fixed Income Report: October 2026
Nov 03, 2026
|
4 min read
Featured Posts
Social Bonds Illustrative Use-Of-Proceeds Case Studies Coronavirus
Jul 06, 2020
|
2 min read
Sustainable Banking Network (SBN) Creating Green Bond Markets
Jul 06, 2020
|
2 min read
Why is Inflation Making a Big Comeback After Being Absent for Decades in the U.S.?
Mar 24, 2022
|
7 min read
SC issues Corporate Governance Strategic Priorities 2021-2023
Mar 29, 2022
|
3 min read
MONTHLY FIXED INCOME REPORT: OCTOBER 2026
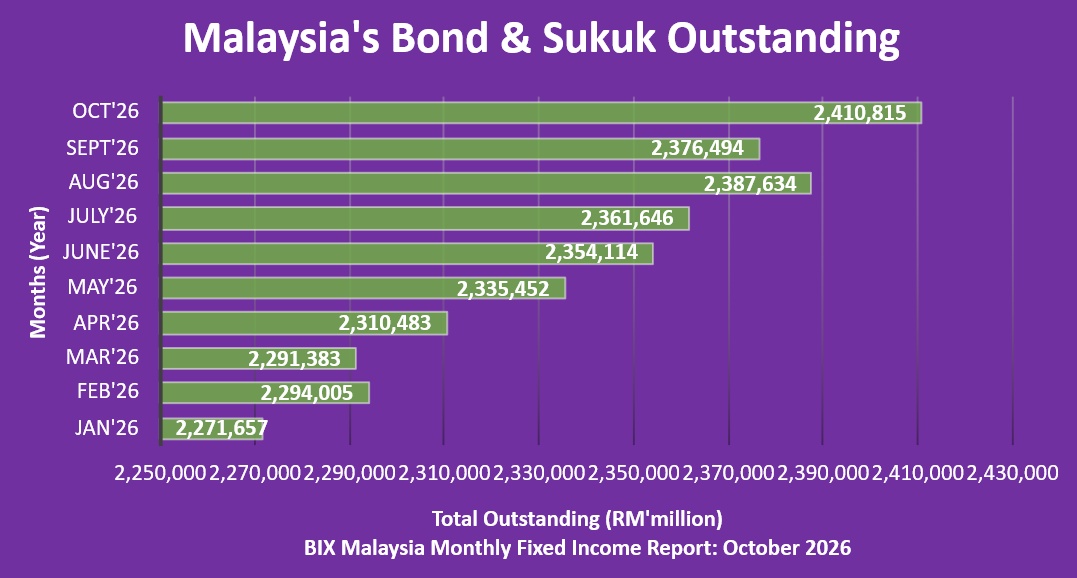
Ringgit Bond and Sukuk Market Stood at RM2.41 trillion Outstanding
In October 2026, Malaysia's ringgit bond and sukuk market recorded total outstanding of RM2.41 trillion, an increase of RM34.32 billion, or 1.43% month-on-month, from RM2.376 trillion in September 2026. On a year-to-date basis, the market grew 6.83% from RM2.256 trillion at the close of 2025, reflecting sustained momentum over the first ten months of the year.
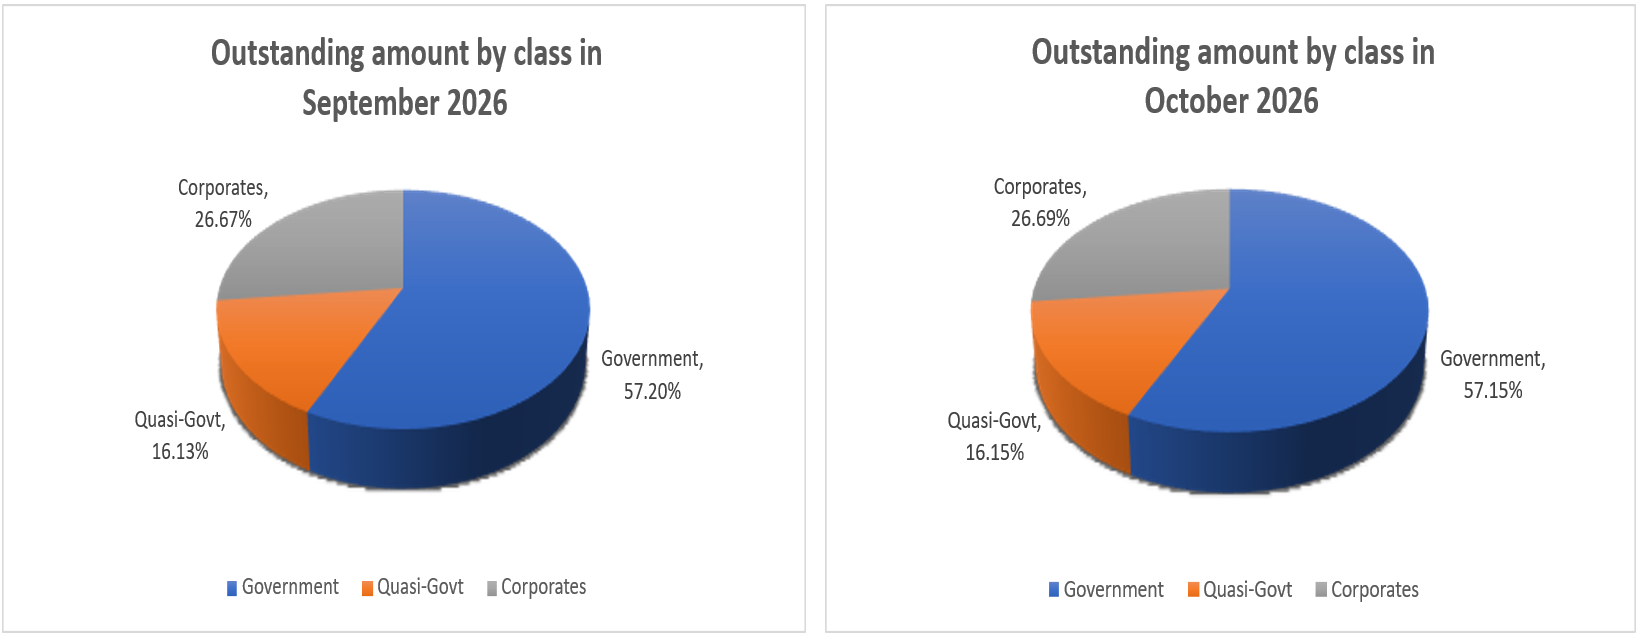
From a structural perspective, government-related issuances remain the market's anchor, accounting for 57.15% of total outstanding paper. This dominant share underscores the sovereign's role in shaping the yield curve and providing reliable pricing benchmarks across all maturities. Corporate issuances contribute 26.69% of the total, while quasi-government entities account for the remaining 16.15%.
.
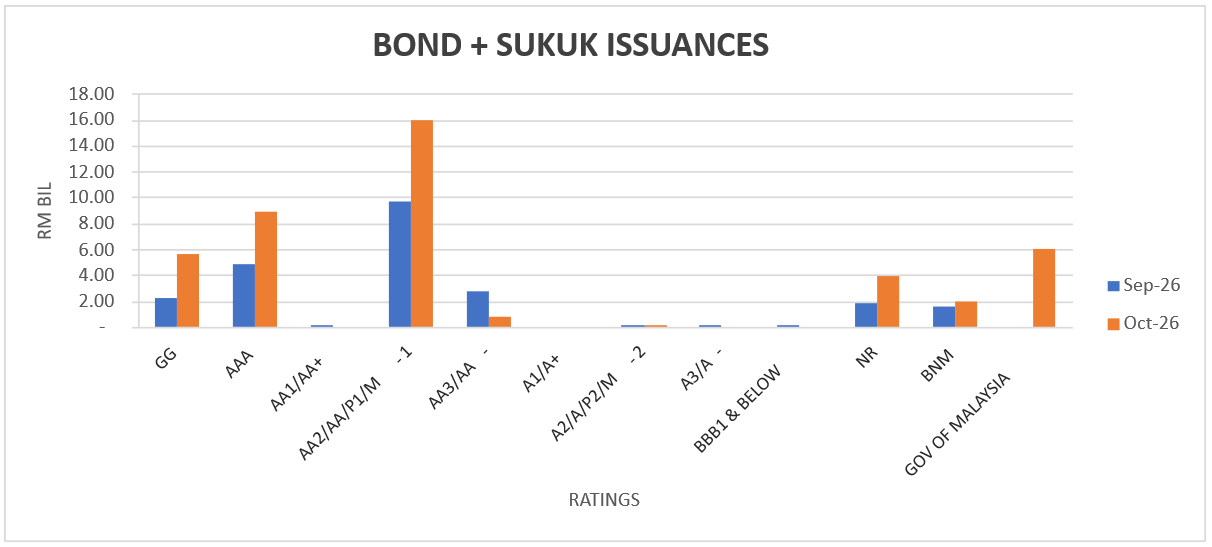
In October 2026, primary issuance activity in the Malaysian bond and sukuk market rose, with total monthly issuances growing 83.28% month-on-month to RM43.42 billion, up from RM23.69 billion in September 2026. AA2/AA/P1/M-1-rated issuances accounted for the largest share, rising 65.74%, or RM6.37 billion, to RM16.06 billion in October 2026 from RM9.69 billion in September 2026. AAA-rated bonds also increased by RM3.99 billion, or 81.43%, to RM8.89 billion in October 2026 compared with the previous month.
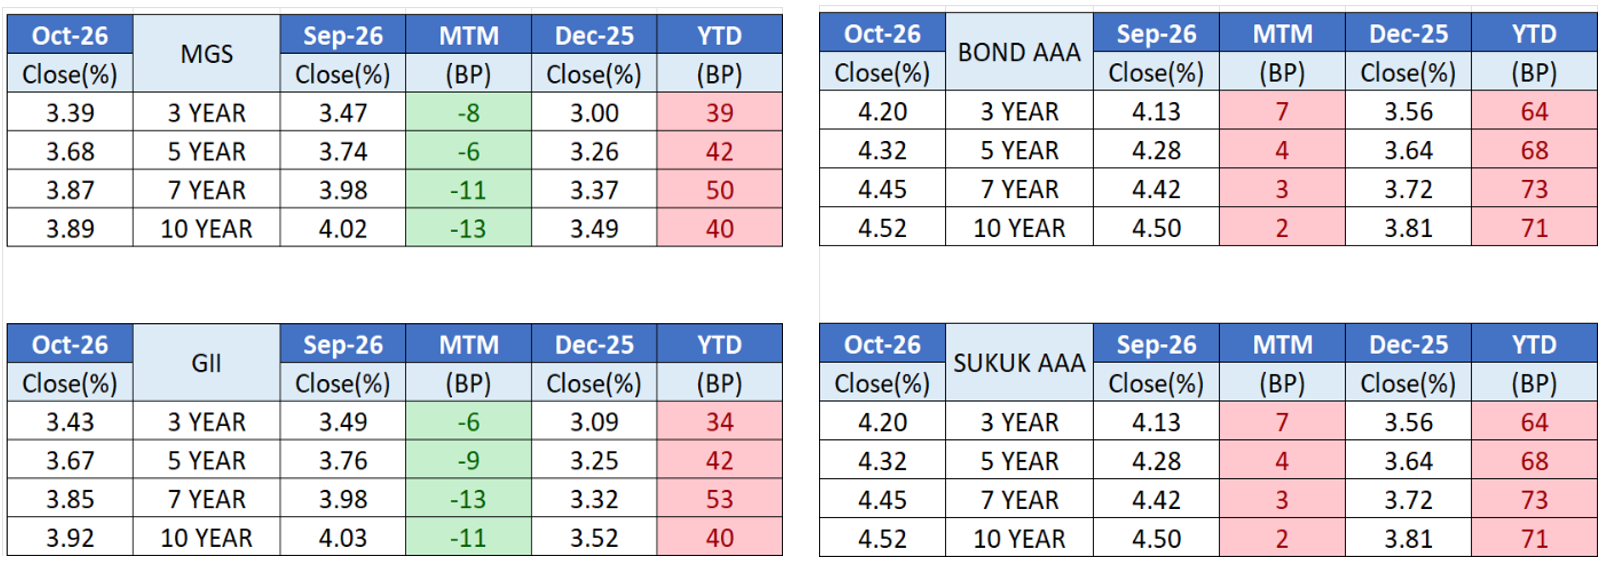
In October 2026, the Malaysian Government Securities (MGS) segment declined across all tenors. The 3-year MGS yield fell 8 basis points (bps) to 3.39%, while the 5-year and 7-year yields dropped 6 bps and 11 bps to close at 3.68% and 3.87%, respectively. At the longer end of the curve, the benchmark 10-year MGS yield declined 13 bps to 3.89%, down from 4.02% in September 2026.
The Government Investment Issue (GII) segment showed a parallel downward trend, with yields falling across all maturities. The 3-year GII yield edged down 6 bps to 3.43%, while the 5-year GII yield decreased 9 bps to 3.67%. The 7-year and 10-year GII yields fell 13 bps and 11 bps to 3.85% and 3.92%, respectively.
The corporate segment moved in the opposite direction, with AAA-rated bonds and sukuk yields rising. The 3-year yield increased 7 bps to 4.20%, while the 5-year yield edged up 4 bps to 4.32%. At the longer end, the 7-year and 10-year AAA yields climbed 3 bps and 2 bps to 4.45% and 4.52%, respectively.
END OF REPORT
3rd November 2026
The information contained in this report is prepared from data believed to be correct and reliable at the time of issuance of this report. While every effort is made to ensure the information is up-to-date and correct, Bond and Sukuk Information Platform Sdn Bhd (“the Company”) does not make any guarantee, representation or warranty, express or implied, as to the adequacy, accuracy, completeness, reliability or fairness of any such information contained in this report and accordingly, neither the Company nor any of its affiliates nor its related persons shall not be liable in any manner whatsoever for any consequences (including but not limited to any direct, indirect or consequential losses, loss of profits and damages) of any reliance thereon or usage thereof.
(201701039928) (1254101-K)
YOU MAY ALSO LIKE
ARTICLE
Nov 03, 2026
|
4 min read
ARTICLE
Sep 02, 2026
|
4 min read
ARTICLE
Aug 03, 2026
|
4 min read
ARTICLE
Jun 04, 2026
|
4 min read